Two forms, nearly identical names, and a filing deadline two months apart. Getting the choice between Form 1099-NEC and Form 1099-MISC wrong is not usually expensive, but it is avoidable, and the rule that decides it is simpler than the forms make it look.
There is also a change for 2026 that most guidance has not caught up with. The dollar threshold that triggers reporting is no longer $600 — for payments made in tax years beginning after 2025 it is $2,000, and from 2027 it will be adjusted for inflation. If you are working from a checklist written before this year, it is wrong.
Quick take: Paid someone for services who is not your employee? That is a 1099-NEC, due January 31. Paid rent, royalties, prizes or other income? That is a 1099-MISC, due to the IRS at the end of February on paper or the end of March electronically. The 2026 threshold for both is $2,000.
The one question that decides it
Ask what you were paying for, not who you paid.
If the payment was for services performed by someone who is not your employee — a freelance designer, a contract developer, a plumber who fixed the office sink, a consultant — it belongs in box 1a of Form 1099-NEC. NEC stands for nonemployee compensation, and that is the entire scope of the form.
If the payment was for something other than services — the rent on your premises, a royalty, a prize, a settlement — it belongs on Form 1099-MISC, in whichever box matches. MISC is the catch-all, which is why it has more boxes and more thresholds.
Both forms are only for payments made in the course of your trade or business. Paying a plumber to fix your own kitchen is a personal expense and is not reportable at all.
What changed for 2026: the threshold is now $2,000
For decades the number was $600. For tax years beginning after 2025, the minimum threshold for reporting these payments increased to $2,000, and beginning in calendar year 2027 it may be adjusted for inflation.
In practice that means a contractor you paid $1,400 across the year no longer gets a form. Two things that do not change:
- The recipient still owes tax on it. The reporting threshold governs your paperwork, not their liability. Income is taxable whether or not a form is issued.
- Several boxes keep their own thresholds. Royalties are still reportable at $10. Gross proceeds paid to an attorney in box 10 of the 1099-MISC are still reportable at $600. Direct sales of consumer products for resale are reportable at $5,000.
Mixed thresholds in one year are the most likely source of a mistake this filing season, so it is worth checking box by box rather than applying one number across the board.
What goes on Form 1099-NEC
- Box 1a — Nonemployee compensation ($2,000 or more): fees, commissions, prizes and awards for services, and other compensation for services performed by someone who is not your employee. Attorneys' fees belong here.
- Box 2 — Direct sales of $5,000 or more of consumer products to a buyer for resale.
- Box 3 — Excess golden parachute payments.
- Box 4 — Federal income tax withheld: backup withholding, covered below.
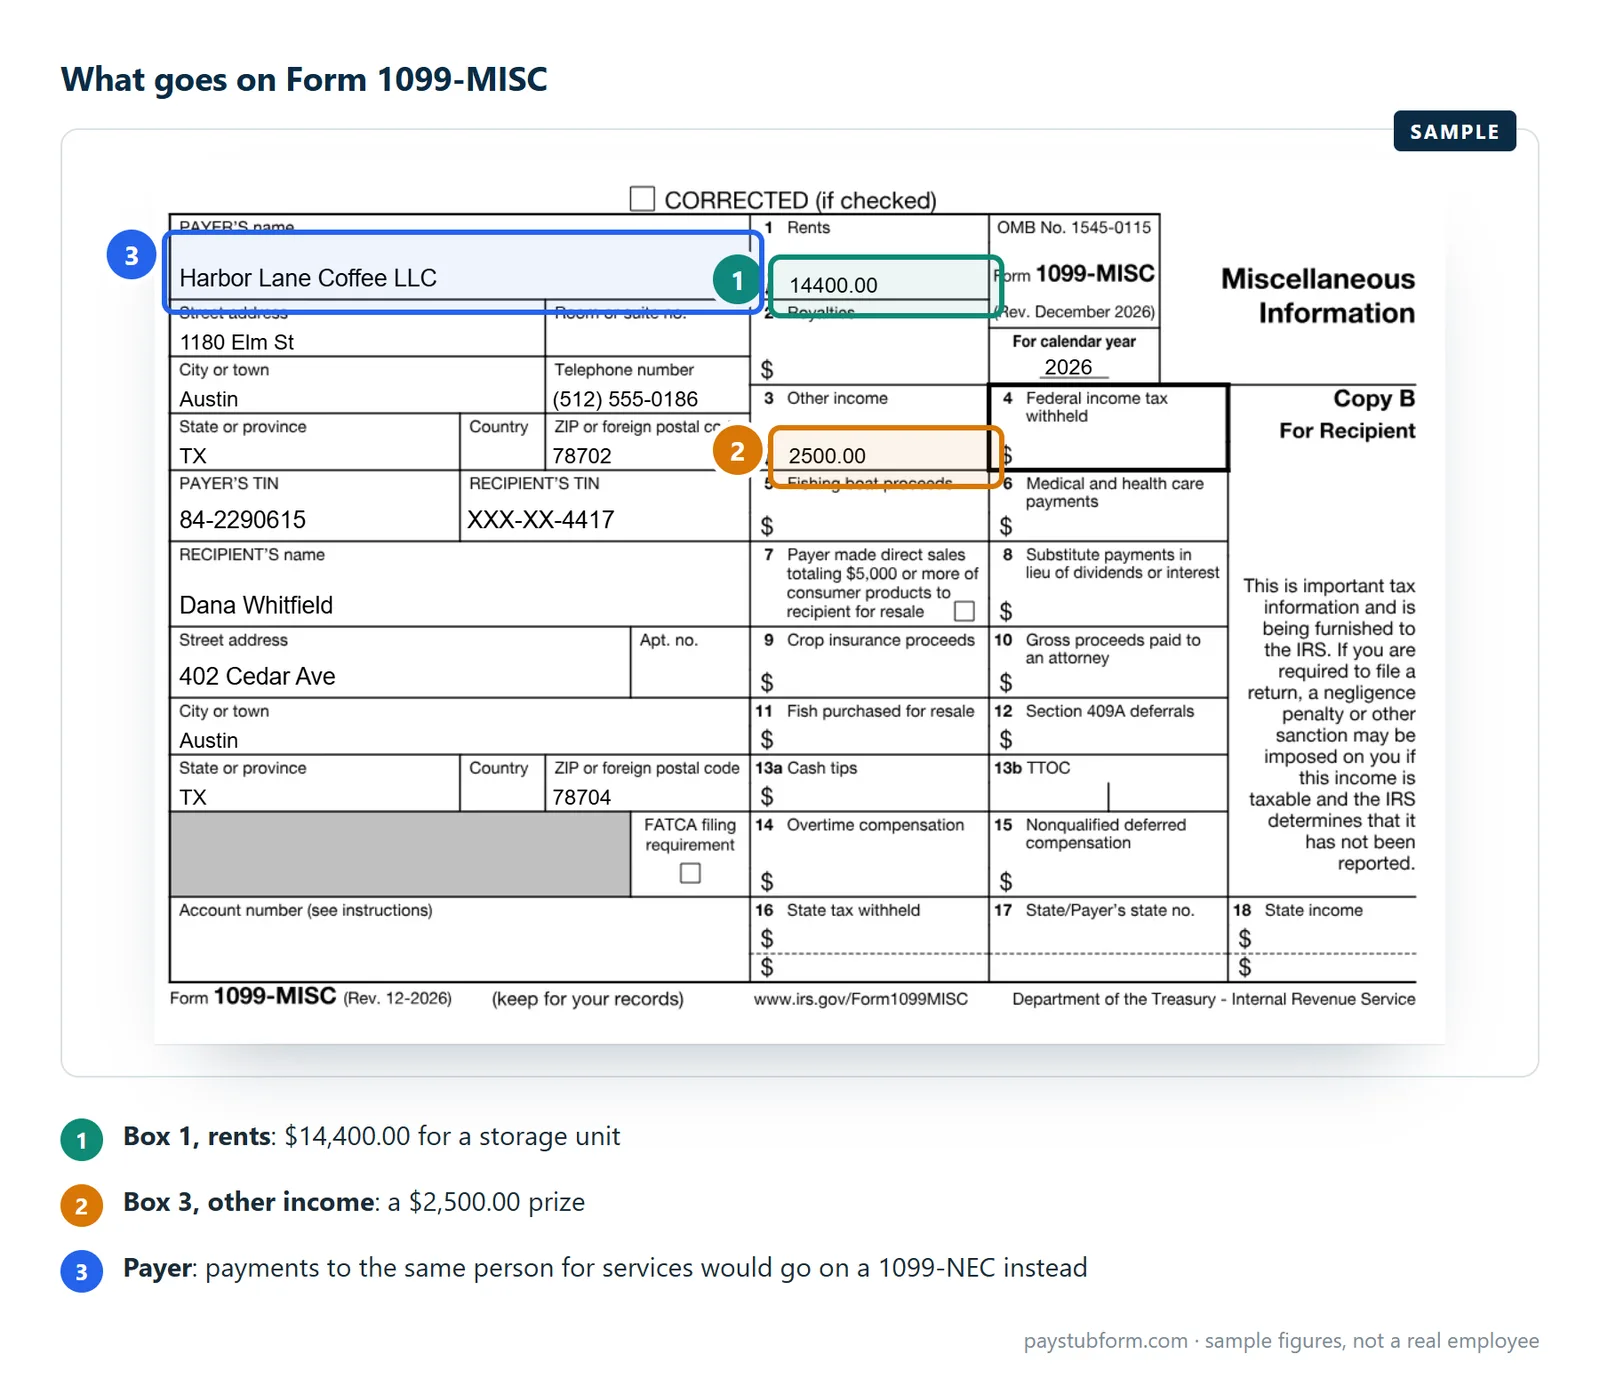
What goes on Form 1099-MISC
| Box | Payment type | Threshold |
|---|---|---|
| 1 | Rents | $2,000 |
| 2 | Royalties | $10 |
| 3 | Other income, prizes and awards | $2,000 |
| 6 | Medical and health care payments | $2,000 |
| 10 | Gross proceeds paid to an attorney | $600 |
The attorney trap
Payments to lawyers are the single most common misfiling, because the same recipient can land on either form depending on what the money was.
Fees for the attorney's own services — you hired them, they advised you, you paid their bill — go in box 1a of the 1099-NEC at $2,000 or more.
Gross proceeds — money that passed through the attorney on its way to someone else, typically a settlement paid into a client trust account — go in box 10 of the 1099-MISC, at a threshold of $600.
Same payee, same year, potentially both forms. The distinction is whose money it ultimately was.
The deadlines are not the same
- Form 1099-NEC: file with the IRS and furnish the recipient copy by January 31. One date for both, and there is no automatic extension worth relying on.
- Form 1099-MISC: recipient copy by January 31, but the IRS copy by February 28 on paper or March 31 if you file electronically.
The January 31 deadline is the reason 1099-NEC exists as a separate form at all: nonemployee compensation was split out of the old 1099-MISC box 7 precisely so it could be matched against returns earlier.
Tip: Collect a signed Form W-9 before you make the first payment, not in January. Chasing a taxpayer identification number from a contractor you no longer work with is the problem that turns a routine filing into a late one.
Backup withholding and box 4
Box 4 on either form reports backup withholding — federal income tax you were required to withhold from a payment that would otherwise be paid in full.
The most common trigger is a missing or invalid taxpayer identification number: someone who has not furnished their TIN is subject to withholding on payments reportable in box 1a. The 2026 backup withholding rate is 24%.
This matters more than it sounds. If you pay a contractor without a W-9 on file and the IRS later finds the TIN was missing, the liability for the tax you failed to withhold can land on you, not on them.
Once you know which form you need, you can fill it out on the official 2026 layout with our 1099-NEC generator or 1099-MISC generator.
What to verify each year
- A current W-9 on file for every payee, with name, TIN and entity type matching.
- Whether each payee is a corporation — payments to corporations are generally exempt from 1099-NEC reporting, with attorneys a notable exception.
- Total paid per payee per calendar year, on a cash basis, against the threshold for that specific box.
- Which form each payment belongs on, decided by what you bought rather than by who you paid.
- Your filing method, because it changes the 1099-MISC deadline by a month.
If you are on the other side of this — receiving the form rather than issuing it — our guide on what a contractor gets instead of a pay stub covers the records that replace payroll documentation.
If some of the people you pay are employees rather than contractors, they belong on payroll and a W-2 instead. Our payroll records checklist for small businesses covers what to keep, and W-2 Boxes 1, 3 and 5 explains what the year-end form reports.
Quick answers
Is the 1099 threshold still $600?
No. For tax years beginning after 2025 it is $2,000, with inflation adjustment possible from 2027. Some boxes keep their own thresholds: royalties at $10, gross proceeds to an attorney at $600, direct sales at $5,000.
Do I report a payment under $2,000?
You are not required to issue a form for it under the general threshold, but the payment is still a deductible business expense for you and still taxable income for the recipient. The threshold governs paperwork, not liability.
Which form does a freelancer get?
A 1099-NEC, in box 1a, if you paid them $2,000 or more for services during the calendar year and they are not your employee.
Do I issue a 1099 to a corporation?
Generally no. Payments to corporations are mostly exempt, but attorneys are reportable regardless of entity type, and medical and health care payments to corporations are reportable as well.
What happens if I use the wrong form?
File a corrected return as soon as you notice. The practical risk with 1099-NEC is less the form choice than the January 31 deadline, since penalties scale with how late the filing is.
Why is there backup withholding on a payment I made in full?
Because the payee had not furnished a valid TIN. Once that applies, 24% of the reportable payment must be withheld and reported in box 4 — which is why a W-9 belongs at the start of the relationship.
Sources
- IRS — Instructions for Forms 1099-MISC and 1099-NEC: the $2,000 threshold effective for tax years beginning after 2025, the box-by-box thresholds, the attorney fee and gross proceeds split, and the filing deadlines.
- IRS Publication 15 (Circular E), Employer's Tax Guide for 2026: the 24% backup withholding rate.
- IRS — Independent contractor (self-employed) or employee?: who counts as a nonemployee in the first place.
General U.S. information, current for the 2026 tax year. Reporting obligations depend on your business and the nature of each payment; for your own filings, speak to a tax professional.


Comments (0)
Loading comments...
Leave a Comment